

Piere: Budget, Plan, Save
UniversTech
- 4.4
- 189.00 Reviews
- 50.00K
- Downloads
- Free
- Price
Screenshots
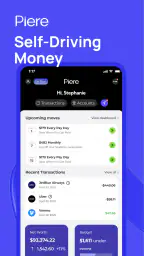
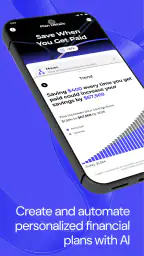
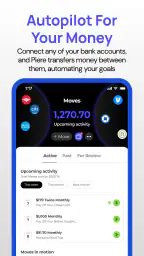
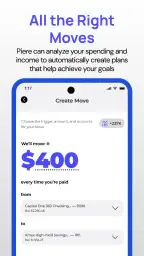
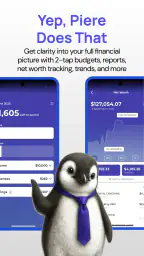
Piere: Budget, Plan, Save Pros and Cons
Pros
- Simple budgeting tools make it easy to track spending and plan ahead.
- Clear visual summaries help you understand where your money goes.
- Savings goals encourage consistent progress toward financial targets.
- Useful reminders can help prevent missed bills and planned payments.
- Clean interface is approachable for users new to personal finance apps.
Cons
- Some advanced budgeting features may require a paid subscription.
- Manual transaction entry can become time-consuming without bank syncing.
- Limited customization may not suit complex household budgets.
- Financial data requires careful privacy review before connecting accounts.
- Syncing or categorization errors may require occasional manual corrections.
 Analysis by All-app
I look at finance apps differently from games or social tools. A budgeting app is invited into parts of life that are easy to mishandle: income, spending habits, recurring bills, savings goals, and sometimes the accounts used to manage them. That makes trust just as important as a pleasant interface. My experience with Piere: Budget, Plan, Save is that it aims to make money management feel less like a weekly spreadsheet chore and more like a routine you can maintain.
Piere is a free finance app from UniversTech, aimed at people who want help organizing a budget and putting savings habits on a more automatic footing. It is available for Everyone and runs on Android with a minimum operating system requirement of Android 10. The app has reached over fifty thousand installs, with a 4.4 average from more than four hundred ratings, so there is enough user activity to suggest that it has found an audience without pretending it is one of the dominant names in personal finance.
That distinction matters. I would not choose this app simply because its store summary sounds convenient. I would choose it if I wanted a focused way to bring budgeting and saving into one place, while remaining willing to inspect the account connections, controls, and paid options before relying on it. The current version is 6.2, and the app feels most useful when treated as an active planning tool rather than a set-and-forget replacement for understanding your own money.
Trust starts with what the app lets you control
I’d begin this section by treating setup as a series of choices, not a hurdle to rush through: connect only what supports the budget you want to manage, and make sure you understand each permission before moving on. That gives the rest of the workflow a clearer foundation. Next, I’d look at which settings deserve a deliberate check before relying on routine automation.
A finance app should make decisions visible
The strongest part of Piere’s concept is the connection between three activities that people often separate: seeing where money goes, deciding how much can be spent, and setting something aside for later. In ordinary life, those decisions affect one another. If a subscription rises or a grocery bill grows, a savings target may need to change. An app that keeps these ideas close together can be more useful than a simple expense diary.
My main test with a tool like this is whether it encourages awareness or merely creates the feeling that everything is being handled automatically. Automation can reduce repetitive work, but it should not hide the reasoning behind a budget. I would want to know which figures are being used, what a planned saving action is based on, and how easily I can adjust or stop it. That is the difference between useful assistance and handing over too much decision-making.
Piere’s appeal is therefore not just that it can help create a budget. It is that the budgeting process can become a regular checkpoint. I can imagine opening it before payday, reviewing the coming commitments, checking whether the current plan still matches reality, and then deciding whether the saving amount remains comfortable. That workflow is more responsible than setting an ambitious target once and never checking it again.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Account access deserves a deliberate setup
Whenever a finance app asks me to connect information, I slow down. I read the permission screens, check which accounts I actually want included, and avoid adding more financial information than the task requires. Piere should be approached with the same discipline. The practical question is not only whether the app can show a useful overview, but whether I understand what I am choosing to connect and why.
This is also where the app may not suit everyone. Someone who prefers to keep all financial information offline may be happier with a local spreadsheet or a simple manual envelope system. That approach takes more effort, but it offers a different kind of control because the user decides where the records live and how they are updated. Piere is better for a person who values convenience enough to consider connected planning, provided that person is comfortable reviewing the available choices carefully.
I would also avoid treating a successful first setup as proof that no further attention is needed. Financial connections can become less useful when accounts change, transactions are unusual, or a payment is categorized in a way that affects the budget. A monthly review is sensible even if the app is doing much of the routine work. Automation should remove repetition, not remove judgment.
Visible choices are more important than impressive promises
The phrase “on autopilot” can sound attractive, but I interpret it cautiously. For me, a trustworthy experience would mean that automatic actions are understandable and manageable: I should be able to see what is scheduled, recognize the amount involved, and know where to change the plan. If an app makes those choices difficult to find, convenience becomes a weakness.
That is why I recommend beginning with a modest budget and a small saving intention rather than immediately building a complicated financial system. A conservative setup gives me time to observe how the app reflects real spending. It also makes mistakes less costly while I learn the workflow. Once the categories and habits feel accurate, I can decide whether more automation is genuinely helpful.
Another practical safeguard is to keep a separate record of important obligations during the first few cycles. Rent, utilities, debt payments, and annual renewals can be easy to overlook when a budget is new. Piere can support planning, but it should not become the only place where I remember a payment that would cause serious trouble if missed.
Data-sensitive moments require patience
The most sensitive moment is the initial setup, because that is when a user is likely to accept prompts quickly just to reach the main screen. I would resist that urge. I would read each request, select only the accounts relevant to my plan, and look for any account-management options available inside the app. The goal is not to be suspicious of every screen; it is to make an informed choice before financial information becomes part of the workflow.
A second sensitive moment arrives when reviewing transactions. Spending records can reveal routines, health-related purchases, travel, family activity, or financial pressure. Even when the app is being used for a practical purpose, I would avoid opening it on a shared device without considering who can see the screen. A strong passcode on the phone and sensible device security remain important because app-level convenience cannot replace basic protection.
The third moment is when a saving plan no longer fits. If income changes or an unexpected bill appears, I would adjust the plan immediately instead of allowing an automatic target to compete with essential expenses. The responsible order is simple: protect necessities first, then rebuild savings. An app can help me notice the conflict, but it cannot decide what matters most in my household.
I also treat paid features with care. Piere is free to install, while in-app purchases range from $1.99 to $79.99 per item. That is a wide enough range that I would inspect the purchase screen before confirming anything and make sure I understand whether a payment is optional for my intended use. I would not assume that every useful budgeting function requires payment, nor would I assume that a paid option is automatically better for my circumstances.
Where user agency matters most
The best use of Piere is as a place where I make decisions with better visibility. For example, imagine I am paid near the end of the month and my account looks comfortable for a few days. Without a forward-looking plan, it is easy to spend that apparent surplus before several bills arrive. I would use the app to separate planned commitments from genuinely available money, then choose a saving amount that leaves room for ordinary surprises.
The non-obvious benefit of that routine is psychological: it changes the question from “Can I afford this today?” to “Does this still fit after the rest of the month?” That is a more useful question than a live balance alone. A transaction-focused banking app may show what already happened, while Piere’s budgeting purpose encourages me to think about what is coming next.
I would also use it before making a recurring commitment. A new subscription may look inexpensive on its own, but the real issue is whether it pushes the monthly plan beyond a comfortable limit. Checking the budget before agreeing to the payment is more effective than discovering the impact at the end of the month. This is a small habit, but it is exactly the kind of habit a planning app should support.
For irregular income, I would be more cautious. A fixed saving target can be sensible when pay is predictable, but it may create pressure when earnings vary. In that situation, I would build the budget around the lower end of expected income and treat stronger months as opportunities rather than guarantees. Piere can be part of that process, but it does not remove the need for conservative assumptions.
Families and couples should also agree on what the app is meant to do before setting it up. A shared financial goal is different from giving another person unrestricted visibility into personal spending. I would establish boundaries first, then connect only what supports the agreed plan. The app may be useful for a common household budget, but the human agreement around access is more important than the dashboard itself.
How it compares with familiar alternatives
Compared with a spreadsheet, Piere should appeal to someone who wants less manual entry and more day-to-day convenience. A spreadsheet remains stronger for custom formulas, unusual financial arrangements, and complete control over the layout. It is also easier to keep entirely separate from connected services. I would pick the spreadsheet when my finances are complex or when privacy and customization outweigh automation.
Compared with a bank’s built-in spending view, Piere has a clearer planning identity. Banking tools are convenient because they already sit beside the account, but they often focus on recent activity and basic categories. A dedicated budgeting app can encourage deliberate limits and saving decisions instead of simply reporting what happened. The trade-off is that another app means another setup, another place to review, and potentially another paid layer.
Compared with a manual envelope method, Piere is less tangible. Physical envelopes make a spending limit feel immediate, which can be powerful for people who overspend when money is mixed together. Piere is more suitable when I want a digital overview and the ability to adjust plans without moving cash between envelopes. If I need a very visible, no-interpretation spending boundary, the physical method may work better.
Compared with a specialist investment or debt tool, Piere appears better suited to everyday budgeting and saving behavior than to deep financial analysis. I would not expect a budgeting workflow alone to replace professional advice, detailed debt modeling, or investment research. Its value is in helping me organize ordinary money decisions, not in turning the app into a complete financial command center.
Small habits that make the experience safer and more useful
My first tip is to start with one clear objective. I would choose either stabilizing monthly spending or building a regular saving habit, then add complexity only after the first objective is working. Trying to track every possible goal immediately can make the app feel demanding and can obscure whether the basic plan is realistic.
My second tip is to review unusual transactions instead of forcing them into a category just to make the budget look tidy. A one-off purchase may not belong in the same place as a recurring expense. Keeping that distinction clear helps prevent a misleading picture of future spending. The point of categorization is not visual neatness; it is better decisions.
My third tip is to schedule a short review after a major life change. A move, a new job, a change in household size, or a large recurring bill can make an old budget inaccurate overnight. I would revisit the plan at that point rather than waiting for the app to reveal that the numbers no longer work.
My fourth tip is to check the purchase controls before exploring premium options. Since individual in-app purchases can be substantial, I would decide what I actually need, confirm the amount at the point of purchase, and avoid buying features simply because the free setup feels incomplete. A paid upgrade should solve a specific problem, not become an automatic part of using a finance app.
Who should use it and who should skip it
I think Piere is a good fit for someone who wants a digital budgeting companion, has enough financial structure to make a plan, and is willing to review connected information rather than blindly trust automation. It may be especially helpful for a person who repeatedly reaches the end of the month wondering where the money went, or for someone who saves inconsistently because the goal is never built into a routine.
I would be less enthusiastic for a person who wants complete offline control, dislikes account connections, or needs highly specialized tools for investments, business finances, complex debt, or detailed tax work. A spreadsheet, a bank’s own tools, or a specialist service could be a better match in those cases. I would also skip it if I expected the app to fix spending without any regular decisions from me.
The age rating of Everyone makes the app broadly approachable, but that does not mean every financial situation is equally simple. Younger users or anyone new to budgeting should still learn the basic difference between available cash, upcoming obligations, and money reserved for a goal. The app can provide structure; it should not be mistaken for financial education on its own.
My cautious verdict
Piere: Budget, Plan, Save is appealing because it brings budgeting and saving into the same conversation. In my view, that is more useful than a tool that only displays past transactions. I like the idea of using it to check what is truly available, plan around upcoming commitments, and make saving a deliberate part of the month instead of an afterthought.
My recommendation comes with a clear condition: I would set it up slowly, inspect every account and purchase choice, and keep reviewing the plan. The app’s convenience is valuable only when I remain the person making the decisions. Use automation to reduce repetitive work, not to surrender financial awareness.
With that mindset, Piere is worth trying for everyday budgeting on a compatible Android device. It is free to begin, has a solid average from its current user feedback, and comes from UniversTech with an active version at 6.2. I would not call it the right answer for every financial need, but for someone seeking a practical bridge between spending awareness and regular saving, it is a sensible app to evaluate carefully.
Frequently Asked Questions
What is Piere: Budget, Plan, Save, and who is it designed for?
Piere: Budget, Plan, Save is a personal finance app designed to help users organize their money in one place. It generally focuses on connecting financial accounts, monitoring spending, creating budgets, and planning savings goals. It may be useful for people who want a clearer overview of their finances without maintaining several spreadsheets, although the available features can depend on your country, bank, and subscription plan.
Is Piere safe to use with my bank and financial accounts?
Before connecting an account, review Piere’s privacy policy, security information, and the permissions requested during setup. Financial apps commonly use secure, read-only connections through third-party data providers rather than asking for your online banking password directly, but practices can vary. Never share verification codes manually, and disconnect accounts or contact support if you notice unfamiliar activity or unexpected access.
What budgeting and planning features does Piere provide?
The app is intended to help you understand where your money goes by organizing transactions, tracking spending, and supporting budget or savings planning. Depending on the version and account type, you may be able to view recurring expenses, compare spending with targets, and monitor progress toward financial goals. Users should check the current feature list because tools and availability may change with updates.
Is Piere: Budget, Plan, Save free, or does it require a subscription?
Piere may offer free access to some financial management tools while reserving additional features for a paid plan, trial, or subscription. Pricing, renewal terms, and included features can differ between Android, iOS, regions, and promotional offers. Before downloading or starting a trial, carefully read the in-app purchase screen, cancellation instructions, and renewal conditions to avoid unexpected charges.
Can I use Piere if I have multiple banks, cards, or investment accounts?
The app is built around giving users a consolidated view of their finances, so it may support connecting multiple institutions and account types. However, compatibility is not guaranteed for every bank, credit union, card provider, brokerage, or country. Connection reliability can also depend on the institution’s security system. Check the supported institutions list and test your most important accounts before relying on the app for complete financial tracking.


